2026 Edition

Automotive Industry Buyer Survey

What Private Investment Firms Are Telling Us About Automotive M&A

Automotive has become a consensus allocation among private investors. Caruso & Co.’s 2026 Automotive Industry Buyer Survey asked 60 private investment firms directly about sector priority, conviction, target verticals, platform thresholds, and acquisition appetite.
The results point to a deep buyer pool today and continued momentum ahead: 58% of respondents rank automotive as a high-priority sector, half expect to increase their focus over the coming year, and three out of four will consider a new platform at $10M of EBITDA or below.

60 private investment firms  ·  10 charts  ·  4-page PDF
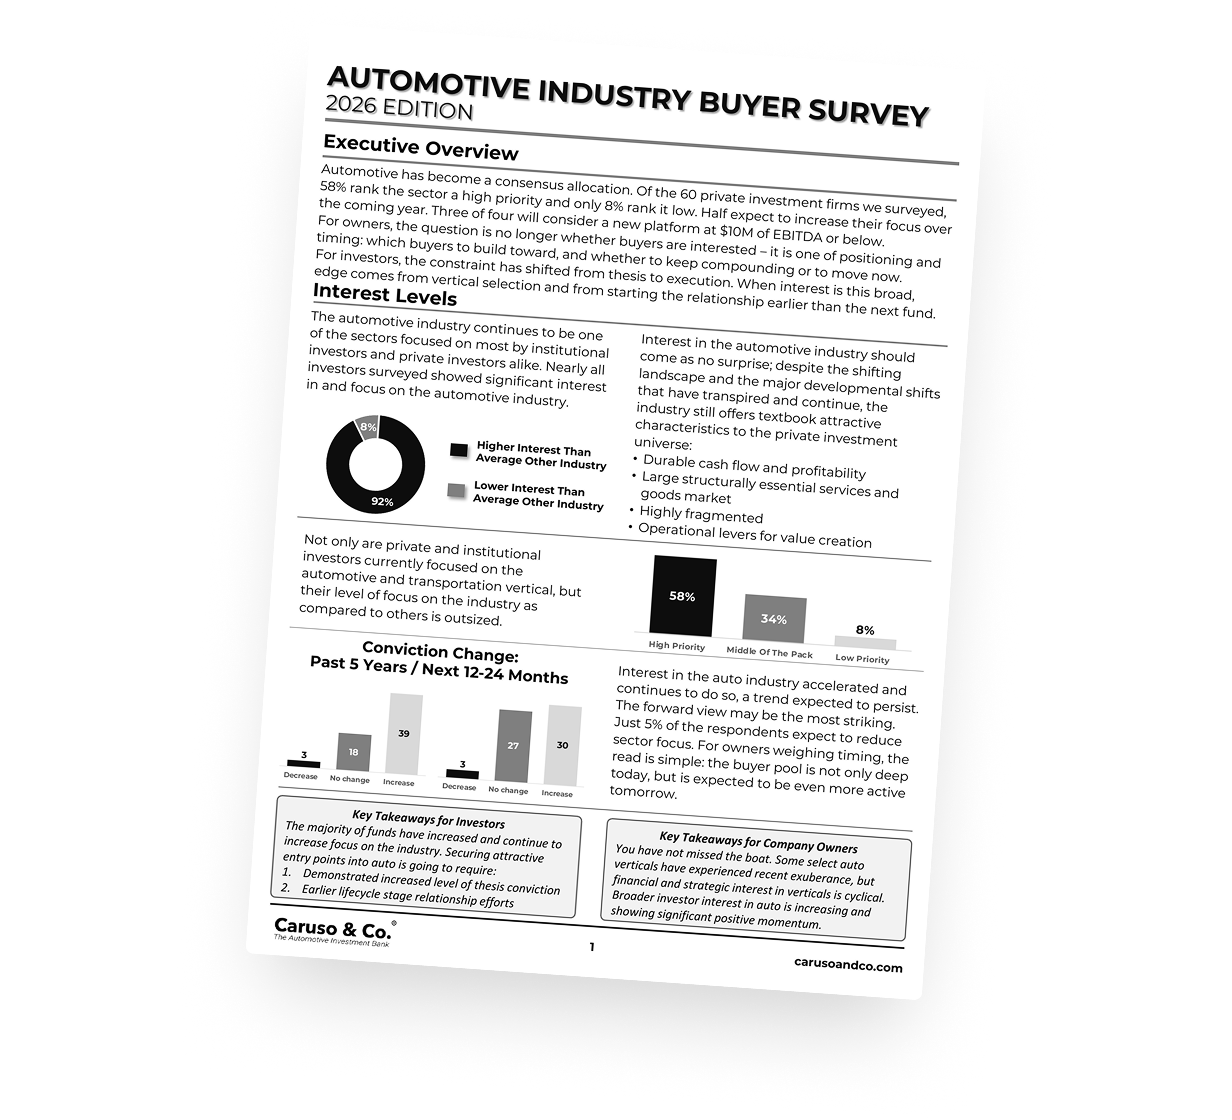
Report page print
A row of new cars parked inside a dealership showroom, featuring a black car in sharp focus upfront

Inside the Survey

4 chapters · 10 charts
→

Executive Overview

The headline numbers: how firms rank automotive, where momentum is heading and the platform sizes buyers will consider.

01

Interest Levels

How firms rank automotive, how it compares with other industries, and where conviction is heading.

02

Focus Areas

Platform vs. bolt-on appetite, the EBITDA threshold buyers underwrite, and interest across 16 verticals.

03

Key Takeaways

What the survey means for automotive M&A, with takeaways for company owners and for investors.

04

Survey Methodology

Who answered: 60 firms by assets under management, active holdings and headquarters, and respondents by seniority.

05

About Caruso & Co.

The automotive investment bank: what we do and our experience.

Executive Overview

Automotive Has Become a Consensus Allocation

Half of respondents expect to increase their focus on automotive over the next 12–24 months, while only 5% expect to reduce it.

For company owners, the question is increasingly less about whether buyers are interested and more about positioning and timing: which buyers to build toward, and whether to keep compounding or move now.

For investors, the constraint has shifted from thesis to execution. When interest is this broad, the advantage increasingly comes from vertical selection and establishing relationships earlier

60
Private investment firms surveyed
58%
Rank automotive a high priority; only 8% rank it low
50%
Expect to increase their focus over the next 12–24 months
3 of 4
Will consider a new platform at $10M of EBITDA or below
Chapter 01 of 04

Interest Levels

Automotive is one of the sectors institutional and private investors focus on most, and interest continues to accelerate.

In this chapter:  Automotivevs.otherindustries  ·  Sectorpriority  ·  Conviction

01

Business professionals signing a contract.
Automotive vs. other industries

Investor Interest in Automotive Remains Outsized

Nearly all investors surveyed showed meaningful interest in the automotive industry. Despite a shifting landscape and major developments across the sector, it still offers the characteristics that make it attractive to private capital:
  • Durable cash flow and profitability
  • Large, structurally essential services and goods markets
  • High fragmentation
  • Operational levers for value creation

Interest in automotive vs. the average other industry

Share of firms

8% 92% higher interest Higher interest than the average other industry 92% Lower interest than the average other industry 8%

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Sector priority

How Firms Rank Automotive Today

Not only are private and institutional investors focused on automotive and transportation, but their level of focus relative to other sectors is outsized.
58%

High priority

34%

Middle of the pack

8%

Low priority

How firms rank automotive as an investment priority

Share of firms

58% 34% 8% High priority 58% Middle of the pack 34% Low priority 8%
58% 34% High priority 58% Middle of the pack 34% Low priority 8%

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Conviction

Conviction Is Increasing

Interest in automotive has accelerated and is expected to remain elevated. The forward view is especially notable: only a small minority of respondents anticipate reducing sector focus.

Change in conviction toward automotive

Number of firms · n = 60 (Decrease: 3 firms in both periods)

Past 5 years Next 12–24 months 39 firms 18 firms 3 30 firms 27 firms 3 Increase No change Decrease
Past 5 years Next 12–24 months 39 firms 18 firms 30 firms 27 firms 3 3 Increase No change Decrease

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Past 5 years

Conviction Has Grown for 39 of 60 Firms

39 firms report higher conviction in automotive than five years ago, 18 report no change and only 3 report a decline.

Next 12–24 months

Half Expect to Increase Their Focus

30 firms expect to increase their focus, 27 expect no change and just 3 (5%) expect to reduce it. For owners weighing timing, the buyer pool is deep today and expected to be even more active tomorrow.

Chapter 02 of 04

Focus Areas

Where buyers want to deploy capital: new platforms over bolt-ons, a competitive center around $5M–$10M of EBITDA, and interest that varies sharply by vertical.

In this chapter:  Platformvs.bolt-on  ·  EBITDAthreshold  ·  Verticalfocus

02
A person analyzing spreadsheets on a laptop and tablet while holding printed financial bar charts at a workspace.
Platform vs. bolt-on

Investors Are Looking for New Platforms

Private investors are seeking new platform investments within automotive more often than bolt-on acquisitions. This is consistent with significant private investment capital (dry powder) still waiting to be deployed, and with investors’ view that automotive and transportation remain large, fragmented and ripe for consolidation.

Platform vs. bolt-on share of investor interest

Share of firms

32% 68% new platforms New platforms Bolt-on acquisitions 68% 32%

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Minimum EBITDA for a new platform

Number of firms · n = 60

45 of 60 firms (3 of 4) at $10M or below Median 2 8 16 19 12 3 <$1M $1–3M $3–5M $5–10M $10–25M $25M+

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

EBITDA threshold

The Competitive Center of the Market Sits Around $5M–$10M of EBITDA

Median minimum platform investment thresholds sit around $5M–$10M of EBITDA. At this level, investment and check size become meaningful enough to attract institutional attention while businesses begin to develop replicable management teams and corporate infrastructure. That said, the survey indicates a motivated buyer set exists for quality businesses across a wide range of sizes.

$5M–$10M

Median minimum platform EBITDA threshold
Vertical focus

Automotive Investor Interest Is Broad, but Highly Vertical-Specific

Interest varies materially across automotive and transportation subsectors. Private and institutional investors appear to hold vertical-specific views rather than one broad automotive thesis.
  • Wide variety in vertical interest; the most cited are Fleet Services (42), Value-Add Distribution (39) and Tire & Auto Repair (33).
  • Services businesses rank highest overall.
  • Profiles differ: a buyer interested in Fleet Services is not necessarily interested in Tire & Auto Repair.

Investor interest by vertical

Firms citing each vertical; totals exceed 60 because firms named several

Fleet Services Value-Add Distribution Tire & Auto Repair Collision / Body Shop ADAS / Calibration Towing Heavy Truck Repair Car Wash Auto Parts Manufacturing Oil Change Auto Software / Tech-Enabled Auto Glass Auto Recycling / Salvage Parking / Mobility Enthusiast Auto Auto Dealership 42 39 33 30 27 27 24 21 21 15 12 12 9 9 9 6

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Chapter 03 of 04

Key Takeaways

What the findings mean for company owners weighing growth or an exit, and for investors competing for the best entry points.

In this chapter:  Executiveconclusion  ·  Forcompanyowners  ·  Forinvestors

03
A person analyzing spreadsheets on a laptop and tablet while holding printed financial bar charts at a workspace.
Executive conclusion

What the Survey Means for Automotive M&A

The survey suggests that automotive is no longer a niche allocation for a small set of specialists. Investor interest is broad, platform appetite remains strong and conviction continues to rise. At the same time, buyers are not treating every vertical or company size the same way.
For owners, understanding who the likely buyers are, what size platforms they underwrite and where their vertical conviction is strongest matters more and more when deciding whether to grow, recapitalize or sell.
For investors, a more crowded market makes sourcing strategy, sector specialization and relationship development more important to successful deployment.
Caruso & Co. is solely focused on the automotive and transportation sector and aims to provide compounding value to owners, executives and investors across the industry.

Takeaways for Owners and Investors

For company owners
Interest levels

You Have Not Missed the Boat

Some automotive verticals have experienced periods of significant activity, but strategic and financial interest moves in cycles. Broader investor interest in automotive is increasing and showing positive momentum.
For investors
Interest levels

Entry Now Requires Conviction and Earlier Relationships

The majority of funds have increased, and continue to increase, their focus on automotive. Securing attractive entry points will increasingly require:
  • Demonstrated thesis conviction
  • Earlier lifecycle-stage relationship efforts
Focus areas

Let Platform Thresholds Guide Grow‑or‑Exit Decisions

  • Use desired platform EBITDA thresholds as a guide when deciding whether to continue growing or pursue an exit.
  • In some cases, management time may be better spent securing an optimal exit and favorable non-compete terms rather than raising additional capital simply to continue growth.
Focus areas

Flexible Thresholds Can Open Less Crowded Opportunities

  • Flexibility and creativity around minimum platform EBITDA thresholds may help avoid the most competitive portion of the market.
  • Understanding relative investor focus across automotive verticals can help determine where resources are best deployed.
Chapter 04 of 04

Survey Methodology

Caruso & Co. surveyed the private equity community directly on priority, conviction, target verticals and investment thresholds, so owners can see the demand side of the market as clearly as buyers see the supply side. The 2026 edition reflects 60 firms across a wide range of assets under management, weighted toward partner- and managing director-level respondents. Firm names were withheld to preserve confidentiality.

In this chapter:  AUM  ·  Seniority  ·  Activeholdings  ·  Headquarters

04
A person analyzing spreadsheets on a laptop and tablet while holding printed financial bar charts at a workspace.

Assets under management

Share of firms

35% 15% 50% under $1B Under $1B $1B–3B $3B+ 50% 35% 15%

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Half of Firms Manage Under $1B

50% of firms manage under $1B, 35% manage $1B–3B and 15% manage $3B+.

Respondent seniority

Share of respondents

35% 25% 15% 25% 60% Partner or MD / Prin. Partner MD / Prin. VP Assoc. / BD 35% 25% 15% 25%

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Half of Firms Manage Under $1B

50% of firms manage under $1B, 35% manage $1B–3B and 15% manage $3B+.

Active holdings and interest level

Number of firms · n = 60

33 15 12 60 firms Yes No, but actively exploring No 33 15 12

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

33 of 60 Report Active Holdings

33 firms report active holdings, 15 are actively exploring the sector and 12 neither hold nor are exploring.

Headquarters by region

Share of firms

Northeast West Midwest Southeast South / Southwest International 45% 15% 10% 10% 10% 10%

Source: Caruso & Co. 2026 Automotive Industry Buyer Survey

Nearly Half Are Based in the Northeast

45% Northeast, 15% West, and 10% each in the Midwest, Southeast, South / Southwest and internationally.
About Caruso & Co.

The Automotive Investment Bank

Caruso & Co. is focused on the automotive industry and advises on select transactions in the $100M–$500M enterprise value range, where complexity, discretion, and buyer access matter most.

What We Do

Sell-side M&A advisory

Sell-Side M&A Advisory

  • Founder-owned representation
  • Sponsor-owned representation
  • Mergers and joint ventures
Capital advisory icon

Capital Advisory

  • Equity advisory
  • Debt advisory
  • Recapitalizations

Our Experience

13+ Years

Investment Banking Experience

$2.8B+

M&A Transaction Value

$1.4B+

Capital Raised

The full report

Download the 2026 Automotive Industry Buyer Survey

The 4-page survey covers:
  • ✓  Automotive investor priority
  • ✓  Sector conviction
  • ✓  Forward-looking investment appetite
  • ✓  Platform vs. bolt-on interest
  • ✓  Minimum EBITDA thresholds
  • ✓  Automotive vertical preferences
  • ✓  Key takeaways for owners
  • ✓  Key takeaways for investors
  • ✓  Respondent demographics and methodology

Caruso & Co. intends to publish the Automotive Industry Buyer Survey annually, building a time series that tracks how investor conviction, sector focus, platform thresholds and acquisition appetite change over time. To take part in the next edition, contact Caruso & Co.

Disclosures

Caruso and Co. LLC, a Wyoming limited liability company, provides comprehensive M&A advisory and brokerage services.
The C&C principal Harry H. Caruso is a registered representative offering securities and investment banking services through Britehorn Securities, a registered broker-dealer (member FINRA/SIPC).

Connect With Us

If you own a mid-sized aftermarket automotive services company and would like to connect, we’re here to help and would be delighted to begin a confidential dialogue today.

Financial advisor reviewing documents with a client.