State of Consolidation by Automotive Industry Vertical
How Consolidated Each Vertical Is, Who Holds the Investment-Worthy Sites and What the Bolt-On Remainder Looks Like
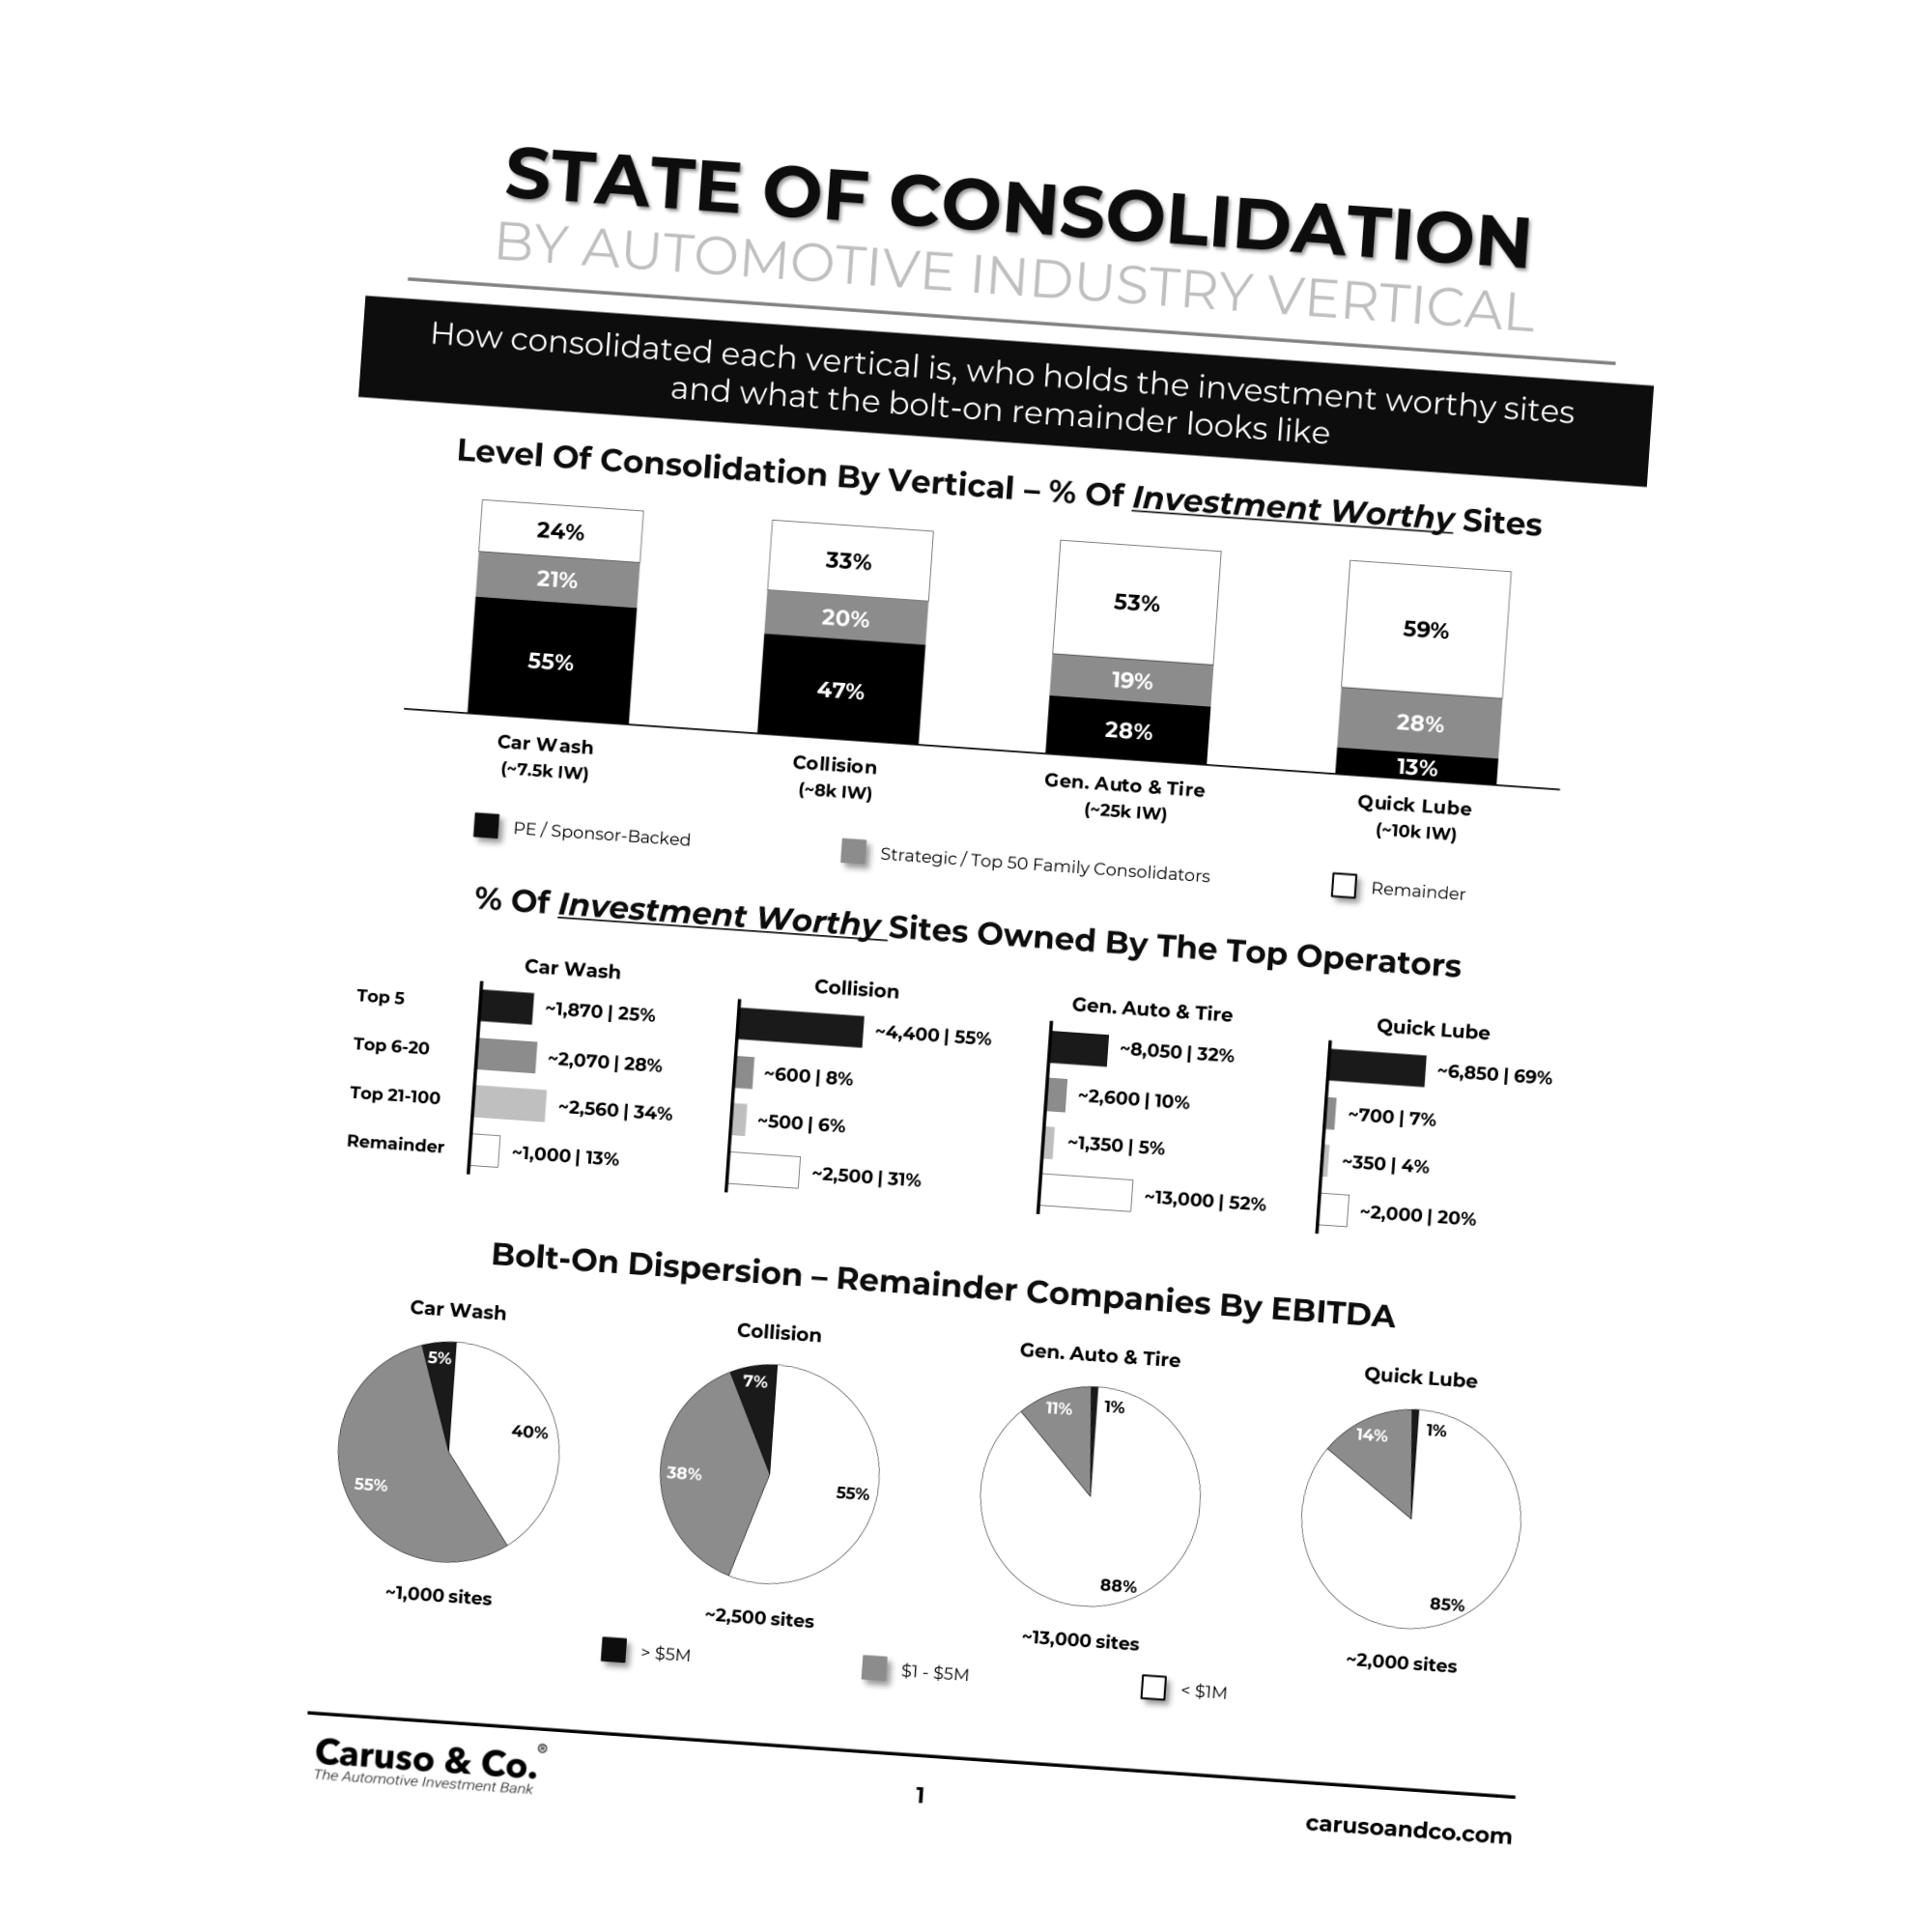
Caruso & Co.’s Fall 2026 State of Consolidation report examines automotive industry consolidation across four major automotive services verticals, showing how much of each investable market has already consolidated, where ownership sits today, and what remains available for future acquisition.
The analysis covers Car Wash, Collision, General Auto & Tire Repair, and Quick Lube, comparing sponsor-backed ownership, strategic and family consolidators, top-operator concentration, the EBITDA profile of the remaining acquisition pool, and the operating thresholds that define an investment-worthy site.
4 Automotive Verticals · 2-Page Report
Executive Overview
Consolidation Looks Very Different Across Automotive Services
The four automotive services verticals represent materially different consolidation profiles. Car Wash and Collision have larger shares of investment-worthy sites under sponsor-backed ownership, while General Auto & Tire and Quick Lube retain significantly larger pools outside the sponsor-backed and major strategic consolidation categories.
The size of the investment-worthy market also varies substantially by vertical, from approximately 7,500 Car Wash sites to approximately 25,000 General Auto & Tire locations.
Investment-Worthy Sites
Investment-Worthy Sites
Investment-Worthy Sites
Investment-Worthy Sites
Level of Consolidation
How much of each investment-worthy market has already moved into sponsor-backed and strategic ownership, and how much remains outside the major consolidators.
In this section: Consolidation by vertical · Investment-worthy site pools

Level of Consolidation by Vertical
Car Wash and Collision Are Further Along the Consolidation Curve
Chart definition: In this chart, “Remainder” refers to investment-worthy sites outside the PE / Sponsor-Backed and Strategic / Top 50 Family Consolidators categories. This is not the same remainder measure used in the Top Operators and Bolt-On Remainder sections.
Source: Caruso & Co. 2State of Consolidation by Automotive Industry Vertical
Top Operators
The headline consolidation percentage tells only part of the story. Looking deeper at the operator rankings shows how concentrated each vertical is among its largest companies and how much of the investable market remains outside the Top 100.
In this section: Top 5 · Top 6–20 · Top 21–100 · Remainder
Who Holds the Investment-Worthy Sites?
Share of Investment-Worthy Sites Owned by the Top Operators
Chart definition: “Remainder” refers to the pool outside the Top 100 operators (see Top Operators). Site counts provide the approximate size of each remainder pool.
Bolt-On Remainder
Not every site outside the largest operators represents the same acquisition opportunity. The EBITDA distribution of the remainder helps show the size and character of the bolt-on pool still available in each vertical.
In this section: Car Wash · Collision · General Auto & Tire · Quick Lube
Bolt-On Dispersion by EBITDA
Investment-Worthy Definition
The investment-worthy universe is not defined by the same operating threshold across every automotive vertical. Caruso & Co. uses vertical-specific revenue and four-wall EBITDA benchmarks to define the site base that institutional buyers and consolidators are more likely to underwrite.
In this section: Minimum revenue per site · Minimum four-wall EBITDA per site
About Caruso & Co.
The Automotive Investment Bank
What We Do
Sell-Side M&A Advisory
- Founder-owned representation
- Sponsor-owned representation
- Mergers and joint ventures
Capital Advisory
- Equity advisory
- Debt advisory
- Recapitalizations
Our Experience
13+ Years
Investment Banking Experience
$2.8B+
M&A Transaction Value
$1.4B+
Capital Raised
The full report
Download the Fall 2026 State of Consolidation Report
- ✓ Level of consolidation across four automotive services verticals
- ✓ Investment-worthy site counts
- ✓ PE and sponsor-backed ownership
- ✓ Strategic and family consolidator ownership
- ✓ Concentration among the Top 5, Top 6–20 and Top 21–100 operators
- ✓ Remaining bolt-on opportunity by EBITDA
- ✓ Minimum revenue thresholds by vertical
- ✓ Minimum four-wall EBITDA thresholds by vertical
Connect With Us
If you own a mid-sized aftermarket automotive services company and would like to connect, we’re here to help and would be delighted to begin a confidential dialogue today.
